How To Guides
Common Misconceptions About Running a Payment Business on White-Label Software
☰What’s in this guide6 sectionsShowHide
Payment software can put a new company in front of merchants much sooner than a custom build. That promise often invites two opposite assumptions: the operator will have almost no control, or the vendor will take care of the whole business. Both lead to poor decisions. A ready-made gateway supplies a technical foundation; the commercial and operational model still needs deliberate choices.
1. White Label Means a Logo on Someone Else's Checkout
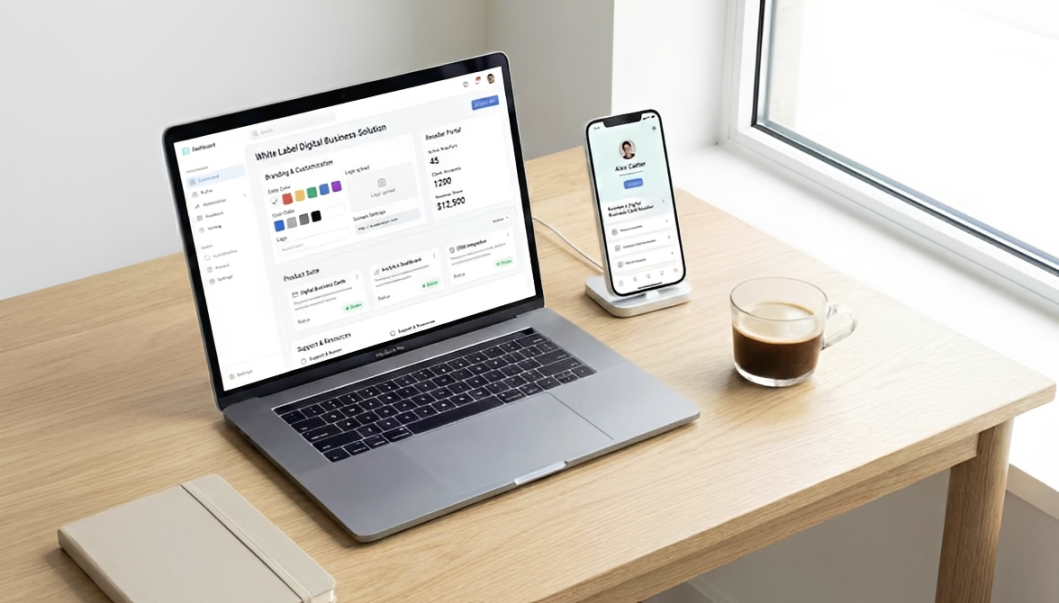
Branding is the visible part, but a payment business also needs a merchant portal, transaction records, routing, refunds, reporting and support tools. A team considering eComCharge can examine how a branded gateway combines these functions with payment orchestration and technical support. The useful question is which parts the operator can configure and which changes require the provider's development team.
Two companies on the same platform can offer different merchant experiences. Their acquiring partners, approval policies, supported payment methods, fee structures and service levels may all differ. A demonstration should therefore follow a real merchant from onboarding through a refund or disputed payment, rather than stopping at the checkout screen.
2. The Provider Takes Over Compliance
Software may include security features, authentication tools and audit records. Those features help, but they do not grant a firm permission to provide regulated payment services or decide whether its merchant controls are adequate.
The applicable obligations depend on what the business actually does and where it operates. In the UK, the FCA's payment institution requirements cover governance, risk management and, where applicable, safeguarding.
Before signing, the operator should map responsibilities in writing:
- Who checks merchants and monitors suspicious activity?
- Who handles incidents, complaints and regulatory notifications?
- Which party controls access to sensitive data and transaction logs?
- Who tests changes to routing rules before they go live?
This is also a practical way to spot gaps between a vendor's technical scope and the firm's own policies. A supplier can support a control without owning the decision behind it.
3. A Fast Platform Launch Means Instant Revenue
A configured gateway can be ready quickly while the commercial operation is still waiting on acquiring contracts, merchant due diligence or approval for particular payment methods. A connector in the catalogue does not automatically mean the operator has permission to send traffic through it. Each relationship has commercial terms, risk limits and a testing process.
Separate the launch into two milestones: a working technical environment and a live service for a defined merchant segment. The second requires agreed partners, tested settlement and refund flows, support procedures and merchants who meet the relevant acceptance criteria. Ask a vendor for a timeline that names these dependencies instead of relying on one go-live date.
4. Shared Software Leaves No Room for Differentiation
Many merchants care more about reliable acceptance and useful service than about who wrote the processing core. An operator can still specialise by market or sector, improve onboarding, build acquiring coverage and give merchants clearer operational help. Technical configuration matters too, particularly when several acquirers serve different transaction types.
The choices worth testing include:
- Routing rules for specific countries, card types or merchant groups
- Merchant-level permissions, reports and fee settings
- Checkout options and local payment methods relevant to the target market
- Data exports that let staff reconcile transactions and investigate failures.
These controls are meaningful only if the operator's staff can use them safely. A complex rule engine without clear ownership, testing and rollback procedures can make troubleshooting harder.
5. Outsourcing the Platform Removes Vendor Risk
A payment firm that uses external software depends on its provider's incident response, release schedule, connector maintenance and ability to supply usable records. Contract terms should cover service levels, access to data, support escalation and an orderly exit.
The European Banking Authority's outsourcing guidelines make clear that institutions and payment institutions retain responsibility for outsourced activities within their scope.
Dependency is manageable when both sides know the boundaries. Ask how a failed acquirer is identified, who can change a routing rule during an incident, how quickly merchant data can be exported and what happens to stored credentials if the contract ends. The answers belong in operating procedures as well as the agreement.
6. White Label Is Always the Cheapest Long-Term Choice
Subscription and setup costs can look modest beside a full internal build. Yet transaction fees, custom connectors, dedicated hosting, extra development and support terms change the total cost as volume grows. Compare realistic scenarios, including a quiet first year and a larger portfolio with several acquirers. Price each scenario against the internal engineering and maintenance effort it replaces.
The decision is ultimately about fit. A white-label platform works best when its existing capabilities match the intended service and the provider can support changes the business is likely to need. Test that fit against merchant workflows, contracts and exit options before treating a fast technical launch as a complete business plan.